Funding gap risk
Why most institutions measure liquidity the wrong way
Static gap reports once sufficed. Then markets turned volatile, liabilities repriced faster than assets, and balance-sheet mismatches became visible only after the damage was done.
We started with a simple observation: the tools used to monitor funding risk were built for a slower era. You deserve measurement that moves as fast as your balance sheet does.
- Static snapshots miss the speed at which liabilities reprice in stressed conditions.
- Cash-flow timing assumptions often ignore embedded options and break clauses.
- Regulatory ratios alone do not reveal the path of vulnerability between reporting dates.
-
Stable +2.4% Net liquidity $4.2BAssets $6.8BLiabilities $2.6B
-
-
Gap ratio 1.62Real-time funding gap coverage updated continuously
-
 0%
Fewer blind spots
From static reports to dynamic models
We replaced quarterly gap schedules with continuous cash-flow simulations that respond to rate shifts, prepayment waves, and contingent drawdowns as they occur.
Explore methodology 0%
Data coverage
Connecting fragmented data sources
Treasury systems, loan servicing platforms, and liability ledgers rarely speak the
same language. We built normalization layers that reconcile them without forcing a
rip-and-replace.
See how it works
 0%
User adoption
Everyday decision support for practitioners
Gap risk is not a quarterly board topic. It is a daily choice about which
liabilities to renew, which assets to pledge, and how far to stretch your liquidity
buffer.
View features
 0%
Early warnings
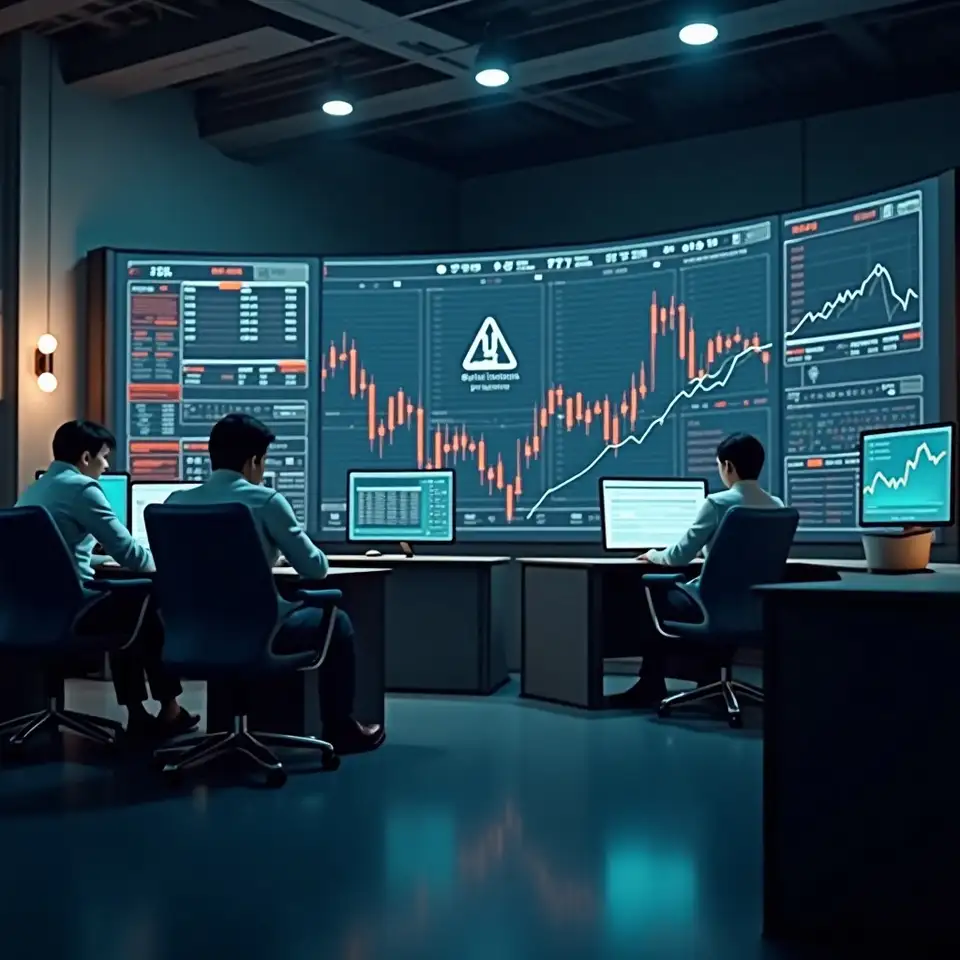
Smart tools that flag what matters
Our alert engine surfaces concentration risk, covenant proximity, and rollover cliffs before they appear in regulatory filings or stress-test submissions.
See alertsWhat we believe about measurement
The antithesis of good risk management is not bad analysis. It is analysis that arrives too late. We have seen institutions run impeccable models on data that was already stale. We have watched committees debate precision while their funding position deteriorated. Our philosophy rests on three commitments: speed without sacrificing rigor, context without drowning in detail, and dynamic measurement that respects the continuous nature of balance-sheet risk.
Cash-flow timing matters more than notional exposure.
Embedded options in liabilities are not footnotes; they are the story.
A model that cannot be explained to a non-quant is a model that will not be trusted.
Regulatory compliance is the floor, not the ceiling, for risk measurement.
Stress is not a single scenario; it is a distribution of paths.
The best metric is the one that changes a decision before the loss crystallizes.
Data quality is a risk discipline, not an IT problem.
Transparency in methodology builds the trust required to act on warnings.
The people behind the platform
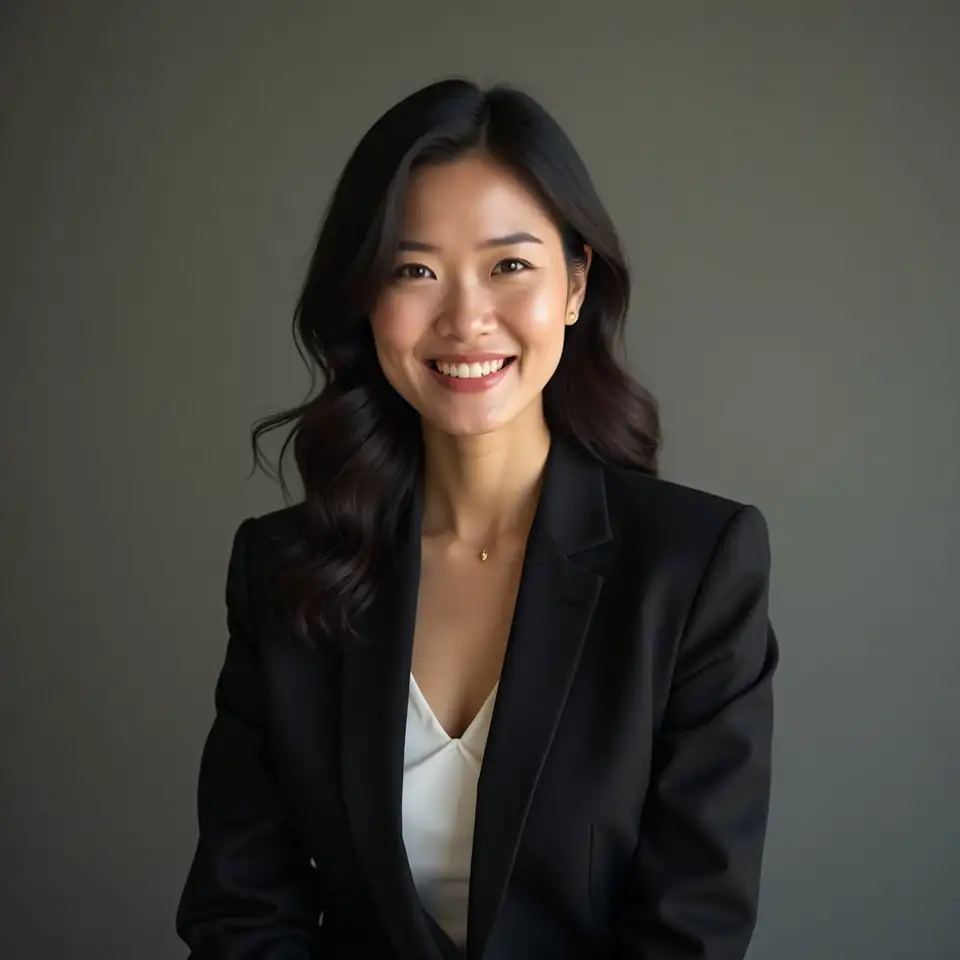
Margaret Chen-Whitmore
Lead Quantitative Risk Architect
Margaret spent fourteen years in treasury risk at two global banks, where she built the first dynamic funding gap engine used in monthly ALCO deliberations. She holds a doctorate in stochastic modeling and believes that the best risk frameworks are the ones practitioners actually use.
stochastic cash flow modeling
ALCO governance design
regulatory stress testing
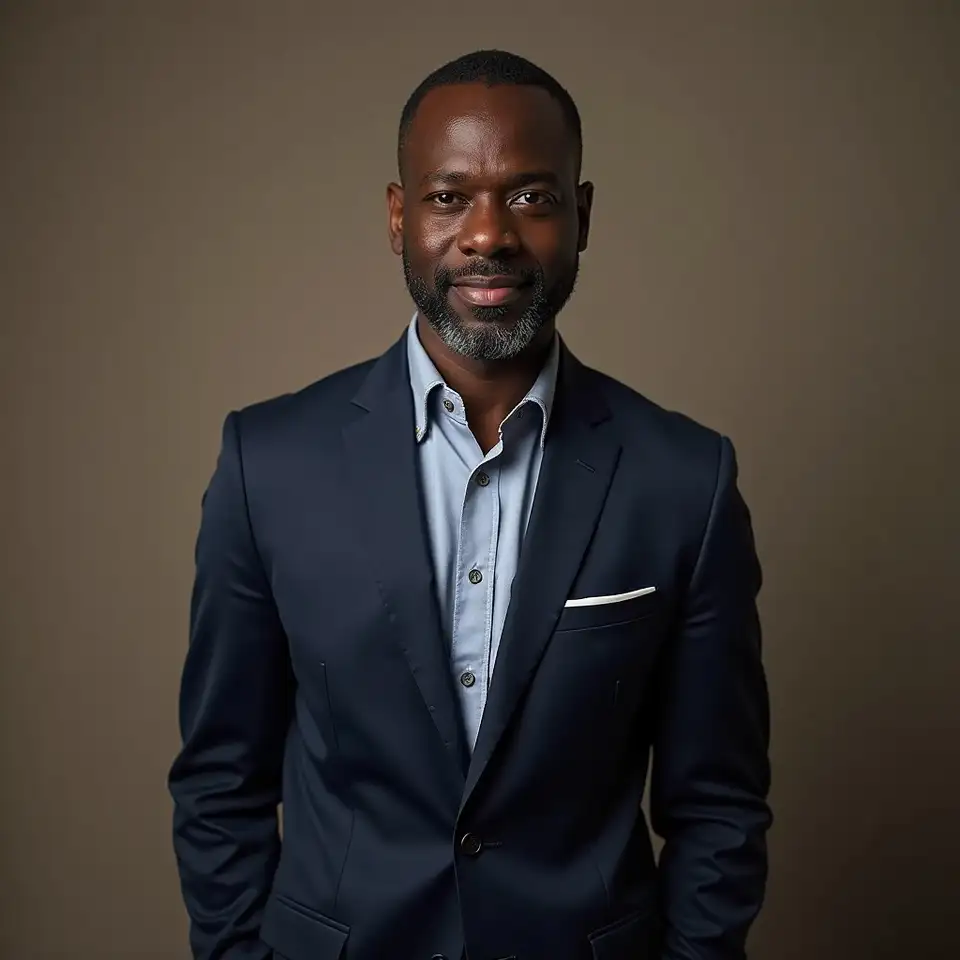
James Oduya-Blackett
Head of Balance Sheet Engineering
James led the build-out of liability pricing infrastructure at a major Australasian trading bank before joining the founding team. He specializes in the behavioral modeling of wholesale deposits and the convexity of committed credit lines under stress.
liability behavior modeling
wholesale funding dynamics
convexity risk analysis
Dr. Sarah Hensleigh
Senior Methodology Advisor
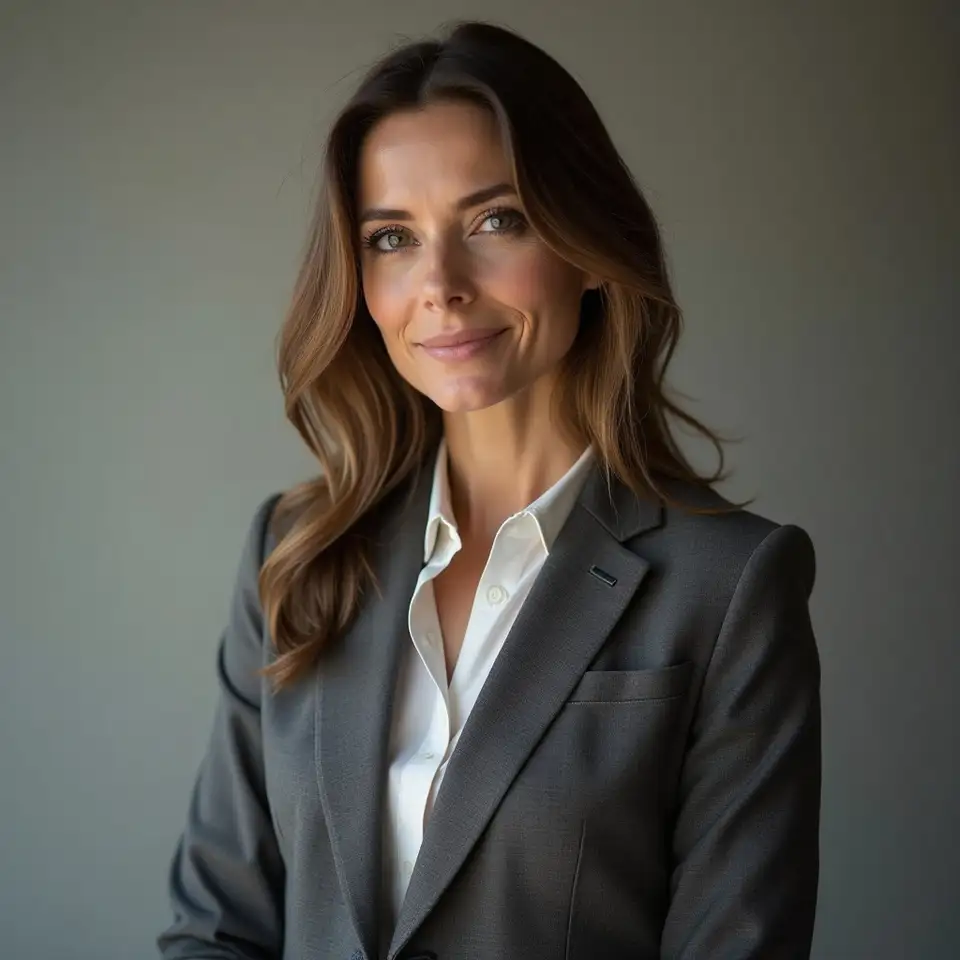
Sarah advises on the statistical foundations of our simulation engines. She previously directed research at a central bank, publishing extensively on funding liquidity metrics and their predictive power during market dislocations.
statistical simulation design
funding liquidity research
market dislocation analysis
Raj Patel-Morrison
Director of Institutional Integration
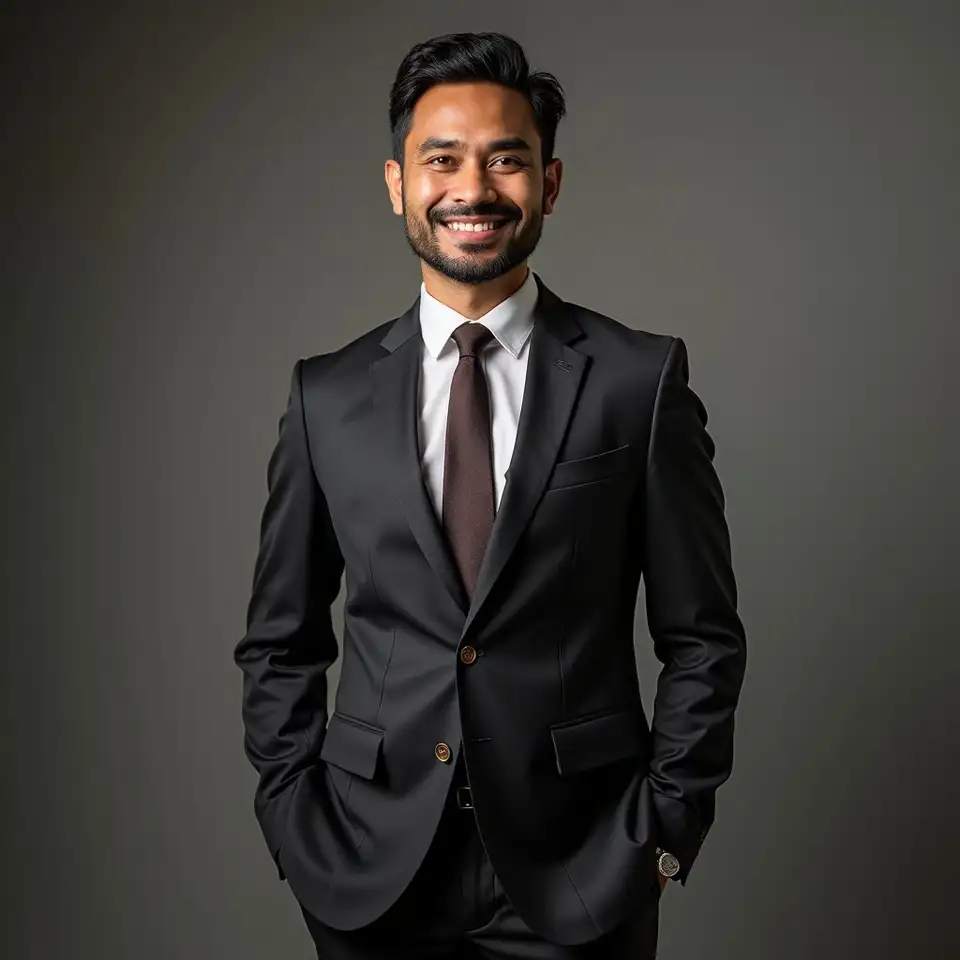
Raj oversees the deployment of our platform across client treasury systems. His background spans enterprise architecture at two custodian banks and a decade of implementing risk data warehouses for regional insurers and asset managers.
enterprise risk architecture
treasury system integration
data warehouse implementation
Recognition and citations
2024
Best Risk Analytics Framework
Honored for advancing dynamic funding gap measurement beyond static regulatory templates.
2023
Distinguished Practitioner Paper
Cited for methodology on continuous liquidity monitoring in volatile rate environments.
2023
Keynote: Funding Gap Dynamics
Invited to present original research on behavioral liability modeling to senior treasury officers.
2022
Innovation in Balance Sheet Risk
Recognized for integrating real-time cash flow simulation with legacy treasury infrastructure.
2022
Emerging Risk Platform
Shortlisted for building practitioner-first tools that bridge quantitative rigor and operational usability.
How we work
Our values are not decorative. They are the constraints we impose on ourselves when building tools that institutions rely on during uncertain times.
1
Intellectual rigor
We do not simplify for simplicity's sake. Every model we publish has been stress-tested against historical episodes, peer-reviewed internally, and documented so that a skeptical auditor can follow the logic from input to output.
2
Practitioner relevance
A model that sits unused is indistinguishable from no model at all. We validate every feature by asking whether it would change a decision in tomorrow's funding meeting, not whether it impresses in a conference presentation.
3
Methodological transparency
We disclose our assumptions, publish our limitations, and welcome scrutiny. Trust is earned when users can see how a number was produced, not just what the number claims to be.
4
Continuous improvement
Balance sheets evolve, markets shift, and so must our engines. We maintain a formal model review cycle, incorporating new data, revised behavioral assumptions, and feedback from practitioners who use the platform daily.